Home
Disciplined wealth management for those who expect more.
Snowwater partners with family offices, ultra-high-net-worth families, and sophisticated investors who value trust, accountability, integrity, and a genuinely personal relationship with their advisor.
-
Assets Under Management
$1.3B+
Across discretionary client relationships as of 12/31/25
-
Advisory
Experience50+ Years
Combined senior team experience -
Regulatory
StatusSEC Registered
Registered investment adviser · fiduciary standard
-
Valued
Clients35+
Client family relationships as of 12/31/25
Who We Serve
Many unique circumstances. One dedicated team
Many unique circumstances. One dedicated team
-
Family Offices
We aim to design your family office around your family's most important circumstances — not a one-size-fits-all package
“One family office platform customized to fit your family's needs.”
What you're navigating
- Disconnected oversight of investments, debt, and liquidity needs due to working with separate teams
- Complex ownership structures, succession, and estate planning
- Uncertainty around next-generation preparedness for wealth transfer and inheritance planning
How Snowwater strives to help
- Investment, Financial, & Tax management — acting as your dedicated team across the family's entities and accounts
- Estate planning coordination — working alongside your attorneys to keep strategy aligned
- Next-generation wealth planning — preparing heirs to understand and steward what they'll inherit
-
HNW & UHNW Individuals and Families
We believe complex wealth requires more than investment management. We help align your investments, tax strategy, estate plan, and family legacy through a single, coordinated approach.
“We tend to the details without ever losing sight of the big picture.”
What you're navigating
- Coordinating multiple advisors and accounts
- Managing tax efficiency as your wealth grows
- Preparing future generations for wealth transfer
- Evolving your financial plan with your lifestyle
How Snowwater strives to help
- Financial & Cash Flow Planning - comprehensive, consistent reporting
- Investment, Tax & Estate Strategy - coordinated approach with tax-management strategies built in
- Multi-Generational Wealth Planning - structuring wealth to transfer efficiently and responsibly
- Risk Management & Charitable Giving - identifying and closing gaps before they matter
-
Business Owners & Entrepreneurs
We help business owners plan for a successful transition and manage wealth long after the liquidity event.“As independent advisors, our goal is to provide advice that fits each client's specific situation — without the agenda of a parent company.”
What you're navigating
- Personal & Business finances intertwined
- Planning for a liquidity event
- Life after the business sale
- Transitioning from income to wealth
How Snowwater strives to help
- Exit Planning - preparing your personal finances ahead of a sale, not after
- Post-Sale Wealth Management - turning a one-time event into a durable, long-term portfolio
- Tax & Legacy Strategy - coordinating personal and transaction-related tax exposure
- Retirement & Asset Protection - protecting a concentrated position until it's diversified
-
Companies & Nonprofit Organizations
Snowwater aims to provide objective investment advice that boards and committees can stand behind — and a partner who reports clearly at every meeting.
“Because we are independent, we are not tied to any firm, particular family of mutual funds, or investment products.”
What you're navigating
- Fiduciary Decision-Making
- Endowment & Reserve Fund Oversight
- Mission-Aligned Investment Strategy
- Independent & Customized
How Snowwater strives to help
- Investment Policy & Governance - a framework that the board and committee can govern by
- Due Diligence & Portfolio Management - grounded in diversification and tactical management
- Tax-Efficient Investment Strategies
- Board Reporting & Independent Custody
-
Pre-Retirees & Retirees
Retirement planning that helps you confidently transition from earning income to living on it.
“Peace of mind through a retirement income distribution strategy.”
What you're navigating
- Turning Savings into Retirement Income
- Long-Term Income Sustainability
- Adapting to Market & Life Changes
- Retirement Confidence & Peace of Mind
How Snowwater strives to help
- Retirement income strategy — a structured approach to drawing down assets sustainably
- Our Managed Income Note Strategy — a customized approach to generating dependable income
- Ongoing monitoring and adjustment — ongoing reviews to keep the plan aligned as things change
- Estate and legacy planning — directing what isn't spent toward the people and causes that matter to you
Where boutique access meets institutional discipline.
We believe the combination of fiduciary alignment, specialized expertise, and hands-on advisory relationships is rare. We are built around it.
-
Institutional Access
We source investments typically reserved for large institutions—structured notes, private placements, and alternative strategies—and make them available to qualified clients. -
Customized Portfolios
No model portfolios. Every investment mandate is built around your specific tax situation, income needs, time horizon, and planning priorities. -
Structured Income & Risk Management
A specialized capability in structured, risk-managed income strategies—providing defined outcomes, downside buffers, and yield enhancement in complex markets.
One relationship, with a full suite of services.
-
Investment Management
Discretionary portfolio management across public equities, fixed income, and alternative strategies. -
Family Office Services
Coordinated reporting, governance, and advisory support for multi-generational families. -
Financial Planning
Integrated planning across retirement, tax, estate, and cash-flow strategy. -
Structured Notes
Specialist access to defined-outcome and income-generating structured strategies.
Why Clients Choose Snowwater
-
What if your financial strategy felt both safer and smarter at the same time?
Always Client-First
-
What difference does it make when your advisor is truly on your side?
Comprehensive by Design
-
Are you getting tailored advice, or is it tied to products and sales goals?
Truly Independent
-
What would it feel like to have complete confidence in every financial decision?
Fiduciary Commitment
A deliberate, structured path from first conversation to long-term partnership.
-
Discover
1
A confidential conversation focused on your goals, current structure, and the full financial picture. -
Create
2
A tailored investment and planning approach informed by your asset mix, income needs, and priorities. -
Implement
3
Disciplined execution across accounts, portfolios, and specialized strategies. -
Monitor
4
Reporting and review through adjustment as markets, tax realities, and priorities evolve.
FAQ
-
What is an RIA / independent financial advisor?
Independent Registered Investment Advisers are professional independent advisory firms that provide personalized financial advice to their clients, many of whom have complex financial needs. Because these advisors are independent, they are not tied to any particular family of funds or investment products. As fiduciaries, they are held to the highest standard of care—and are required to act in the best interests of their clients at all times. They are registered with either the Securities and Exchange Commission or state securities regulators.
-
What does being a Fiduciary mean?
A fiduciary is a professional entrusted to manage assets or wealth while putting the client’s best interests first at all times. Financial advisors who follow a fiduciary standard must disclose any conflict, or potential conflict, to their clients prior to and throughout the advisory engagement. Fiduciaries will also adopt a code of ethics and will fully disclose how they are compensated. -
What separates us from other financial advisors?
As an independent Registered Investment Advisor, we are free to provide advice that fits each client’s specific situation and needs without concerning ourselves with the agenda of a parent company. Our services range from financial planning to investment management to estate planning—we can meet a wide range of needs under one roof. Finally, we are oriented toward providing each client the attention and service they deserve. We treat our clients as individuals and not numbers. -
Where is my money kept?
In our advisory role, we never take custody of client assets. We work with institutional partners like Charles Schwab, Fidelity, JP Morgan, and Citi as the custodians of client accounts and as our primary brokers. Our partnership with these firms is an arm’s-length transaction with no exchange of funds between us. Clients provide us with limited trading authorization on their accounts. This authority allows us to process trades directly in client accounts.
-
How do I move my assets?
Typically, we only need a copy of your most recent account statement and your signatures on a few forms. We will take care of setting up your new account and transferring your assets. -
Why is comprehensive wealth management important?
High-quality financial decisions rarely exist in isolation. Integrating investment management, retirement planning, tax considerations, and legacy planning into a coordinated strategy can help improve decision-making and support long-term financial success.
-
Frequently used terms: structured note, contingent downside protection, coupon, UHNW, OCIO, ESOP and CAIA.
Structured Note
A customized investment product that combines a bond with one or more derivatives. Returns are typically linked to the performance of an index, stock, interest rate, or other asset and may offer features such as enhanced income or downside protection.Contingent Downside Protection
A feature in some structured investments that protects against losses up to a specified level, provided certain conditions are met. If the underlying investment declines beyond a predetermined threshold, investors may experience losses.Coupon
The income or interest payment an investor receives from a bond or structured note, usually expressed as an annual percentage rate.UHNW (Ultra-High-Net-Worth)
Refers to individuals or families with very substantial investable assets, commonly defined as having $30 million or more in net worth (excluding primary residence).OCIO (Outsourced Chief Investment Officer)
A service model in which an external investment firm assumes responsibility for some or all investment management functions, including asset allocation, manager selection, portfolio monitoring, and reporting.ESOP (Employee Stock Ownership Plan)
A qualified retirement plan that provides employees with ownership interests in their company through company stock, helping align employee and shareholder interests.CAIA (Chartered Alternative Investment Analyst)
A globally recognized professional designation focused on alternative investments, including private equity, hedge funds, real assets, structured products, and other non-traditional asset classes.
Insight from our advisors.
Contact Snowwater
-
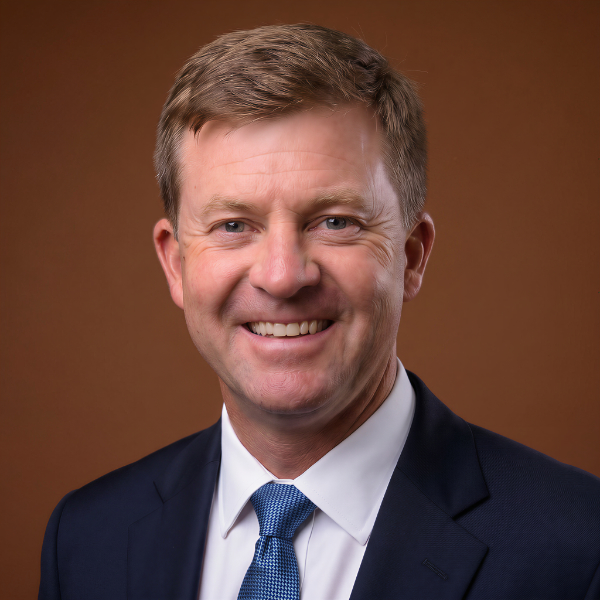
Brad Orben
Founder and Managing Partner
-
Victor M. Flores
Managing Partner